Lessons from the 2022 Queensland and NSW Floods
The 2022 South East Queensland and Northern New South Wales floods are one of the clearest examples I've encountered of how underinsurance plays out in practice, not in theory. I want to share this case study because it captures a pattern I see often in my work: a building that looks adequately insured under normal conditions, and a funding gap that only becomes visible once a disaster hits. It's a valuable lesson for any owner who hasn't reviewed their insured value recently.
The 2022 Floods and Their Aftermath
In February and March 2022, major flooding impacted South East Queensland and Northern New South Wales, causing widespread destruction to residential, commercial and industrial assets. The floods drove a surge in demand for the trades and materials needed to rebuild, at a time when the construction market was already under pressure. This combination pushed reconstruction costs well beyond pre-flood expectations.
Demand rose sharply for:
- Builders and tradespeople
- Engineers
- Quantity surveyors
- Building materials
- Temporary accommodation
This occurred against a backdrop of labour shortages and rapidly escalating material prices, conditions that were already stretching the construction sector before the floods hit.
A Typical Underinsurance Scenario
Here’s a scenario I see often. Consider a commercial building owner who insured their property based on a valuation completed several years earlier.
Before the Flood
| Item | Amount |
|---|---|
| Building Insured For | $10,000,000 |
| Actual Reinstatement Cost at Date of Loss | $13,000,000 |
At first glance, the owner is already underinsured by $3 million.
After the Flood
Once a major event hits a whole region rather than a single property, I've seen the gap widen further still. Neighbouring properties compete for the same contractors, materials and trades, reconstruction periods lengthen, and prices rise on demand alone.
The actual replacement cost may climb further:
| Item | Amount |
|---|---|
| Original Sum Insured | $10,000,000 |
| Cost to Rebuild After Disaster | $15,000,000 |
| Funding Gap | $5,000,000 |
Suddenly, the owner must find an additional $5 million to return the asset to its former condition, at exactly the point they can least afford to.
The Underinsurance Gap
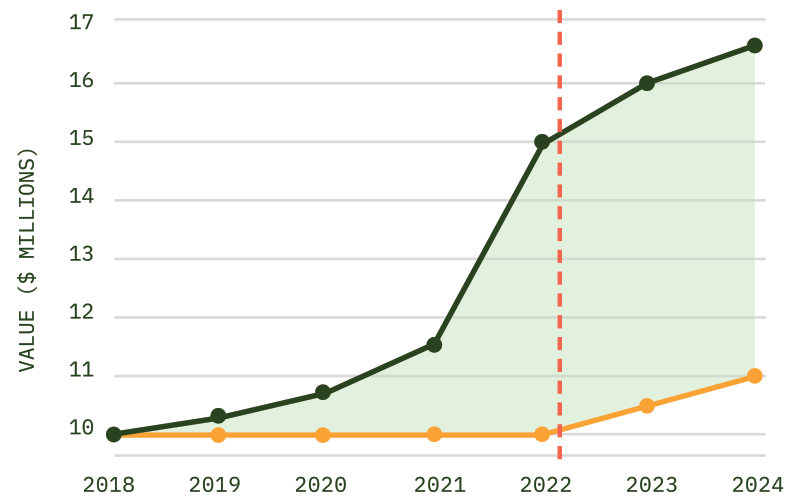
Legend: Orange Line = Insurance Cover (remaining relatively static over time). Green line = Actual Reinstatement Cost. Red dashed line = Major natural disaster event. Green shaded area = Underinsurance gap
Before Disaster (2021)
Insurance Cover: $10M
Reinstatement Cost: $13M
Shortfall: $3M
After Disaster (2022)
Insurance Cover: $10M
Reinstatement Cost: $15M
Shortfall: $5M
Result: The owner must source an additional $5M to fully reinstate the asset.
What a Quantity Surveyor Sees
In my experience, underinsurance rarely occurs because owners intentionally choose insufficient cover.
More commonly, it occurs because insured values are left unreviewed for years while several cost drivers move without them
- Construction Cost Inflation: labour rates, steel, concrete, and mechanical and electrical services all rise over time, often unnoticed until a claim forces a recalculation.
- Demolition and Debris Removal: a total loss requires demolition, waste disposal, hazardous material management and site clearing, costs that are frequently overlooked.
- Professional Fees: architects, structural and hydraulic engineers, certifiers, quantity surveyors and project managers are all genuine reconstruction costs. Our own insurance methodologies at Acumentis build allowances for professional fees, demolition, contingencies and escalation into every assessment.
- Post-Disaster Escalation: often the biggest issue of all. A building can be adequately insured the day before a disaster and effectively underinsured the day after, once regional demand pushes rebuilding costs up.
Acumentis insurance templates specifically recognise that natural disasters can generate labour and material shortages and create an inherent risk of underinsurance.
Real Consequences for Owners
When underinsurance meets a major disaster, I've seen the impact play out differently depending on the asset:
Strata Buildings
- Special levies imposed on owners
- Delayed reconstruction
- Reduced scope of rebuilding works
Commercial Buildings
Industrial Assets
- Operational shutdowns
- Relocation costs
- Loss of production capacity
- Significant capital injections by owners
"When a disaster affects a single building, reconstruction occurs within a functioning market. When a disaster affects an entire region, the market itself changes. Labour becomes scarce, materials become constrained and construction costs can escalate rapidly. The difference between an insured value and a true reinstatement value can determine whether recovery is achievable or financially devastating."
Key Takeaway
The lesson from events such as the 2022 Queensland and NSW Floods, Cyclone Yasi, and other major Australian catastrophes is that reconstruction costs are often highest immediately after a disaster, precisely when an insurance policy is called upon.
A property may appear adequately insured under normal market conditions, but if the insured value does not include demolition, professional fees, escalation allowances and current replacement costs, a major natural disaster can expose a multimillion-dollar funding shortfall.
My advice to owners is simple: get your reinstatement valuation reviewed well before conditions change, not after.
"Replacement cost can increase dramatically after a catastrophe because everyone is rebuilding at the same time."